For parents and instructing solicitors, as the autumn term begins
Who pays school fees after separation?
The responsibility for the payment of school fees is decided by agreement or by court order. An order to pay the fees as invoiced by the school will usually include the 20% VAT introduced for terms from 1 January 2025. However, an order for a fixed sum or a capped payment will not, and the shortfall falls on the other parent. The liability to the school is a separate issue and is determined by the enrolment contract: where both parents are parties to it they will commonly be jointly and severally liable. The court order allocates responsibility between the parents but does not bind the school.
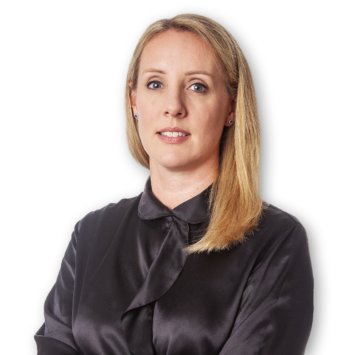
Suzanne Syme MCIArb
Barrister, Harcourt Chambers
Called 2004. Recognised in Chambers UK Bar 2026, The Legal 500 UK Bar 2026 and Spears.
Suzanne has specialised in matrimonial finance and the financial consequences of relationship breakdown since pupillage. Her expertise includes claims under Schedule 1 of the Children Act 1989 and TOLATA 1996. She has a particular interest in school fees orders and pension provision on divorce. She was appointed a Financial Arbitrator in 2017 and is a member of the Family Law Bar Association and the Chartered Institute of Arbitrators. She read law at Queen Mary, University of London and was a Major Scholar of the Inner Temple. She has had a number of reported cases and appeared as junior counsel for the respondent mother in Tracey v Tracey [2006] EWCA Civ 734, in which the Court of Appeal reconsidered the capitalisation of a school fees order.
View full profileThe issues surrounding the payment of school fees usually surface shortly before the start of a school year. An invoice arrives, an increase lands, and an arrangement that worked last year stops working. This guide covers what an existing order is likely to cover, who is liable to the school, and what practical steps can be taken to resolve any issues.
The family-law analysis in this guide applies to England and Wales. VAT applies across the UK, but family law in Scotland and Northern Ireland differs.
Where Does the VAT Position Stand?
VAT at 20% has applied to private school fees for terms starting on or after 1 January 2025, under sections 47 to 49 of the Finance Act 2025.
There have been two challenges to the issue based upon an alleged conflict with human rights, in R (ALR and others) v Chancellor of the Exchequer [2025] EWHC 1467 (Admin) and in the Court of Appeal in R (BYL) v Chancellor of the Exchequer [2026] EWCA Civ 170. The Supreme Court has listed the appeal for 1 and 2 December 2026.
A successful appeal would not itself remove the tax or create an automatic entitlement to refunds. The challenge is to compatibility with the European Convention, not the provision’s validity. The likely remedy is a declaration of incompatibility under section 4 of the Human Rights Act 1998, which does not affect the validity or continuing operation of the provision, although a subsequent governmental or parliamentary response cannot be ruled out. Families facing an immediate affordability problem should not delay solely because of the Supreme Court appeal.
Does an Existing Order Already Cover the VAT?
This is a question of construction, turning on the drafting of the provisions of the order itself, with a focus upon the words defining the obligation rather than what the parties assumed. No reported family judgment has yet decided it, so what follows is the better construction rather than settled law.
| Wording in the order | VAT falls on the payer? | Why |
|---|---|---|
| “The school fees as invoiced by the school” | Usually yes | VAT forms part of the sum invoiced. |
| A fixed annual sum, or a cap | No | Liability stops at the figure stated. The shortfall falls on the receiving parent. |
| “Basic fees, exclusive of extras” | Usually yes, but arguable | VAT taxes the supply of education, not an optional extra like trips or music lessons. |
The effect of a cap is stark. An order capping liability at £18,000 a year against a net fee of £16,500 looked generous in 2022. With VAT the invoice is £19,800, leaving the receiving parent £1,800 short each year. The order now does the opposite of what it was designed to do.
There are two areas in which the practitioner should focus upon when preparing a school fees order to future-proof the order, in so far as possible (i) defining each party’s responsibility for the payment of the fees and (ii) ensuring there is a mechanism in place to meet the future cost of any extras incurred on the bill.
Additional issues may arise if the parties have agreed to pay a lump sum to discharge the school fees in advance. Who is responsible for any additional future costs, and if there is no agreement, how should the dispute be resolved?
Who Is Liable to the School?
There is no single document that determines every aspect of school-fee liability. Three instruments are often confused: the parent contract with the school, any third-party guarantee, and the school fees order made by the court.
The liability to the school will be dependent upon the enrolment contract. Where both parents are parties to it, they will commonly be jointly and severally liable for the whole of the fees, so the school may pursue either for the entire sum. Where only one signed, the school may be limited to that signatory. These contracts typically require one full term’s notice to withdraw a child, with fees payable in lieu.
The court order allocates responsibility between the parents but does not bind the school, which is not a party to it. The school terms that they publish expressly state this provision. So the starting point is to read the order, then the contract, and establish who signed.
Are School Fees Part of Child Maintenance?
The basic level of child maintenance does not include provision for the payment of school fees. However, in cases where there is an application for a ‘top up’ order, school fees can be factored into the calculation.
The CMS retains jurisdiction for child maintenance on gross income up to £156,000 a year. Any income received above that is automatically ‘capped’. Many lay parties are unaware of this automatic cap, or that they can make an application for a top-up order either within their financial remedy proceedings or separately under Schedule 1 of the Children Act 1989.
The algorithm for the payment of child maintenance and school fees is known by practitioners as the ‘James v Seymour calculator’ following the decision of Mostyn J in James v Seymour [2023] EWHC 844 (Fam). The judgment outlines the approach that should be adopted by the Court (albeit not in variation cases), and produces the formula for the calculation.
When Can a School Fees Order Be Varied?
In circumstances where there are financial remedy proceedings (within the context of a divorce), a school fees order is made as periodical payments for a child under section 23 of the Matrimonial Causes Act 1973. This order can be varied under s31. A lump sum order is not variable.
If the school fees issue was not determined during the financial remedy proceedings, or where the child’s parents were not married, either parent can make an application for a school fees order under Schedule 1 of the Children Act 1989.
The test under Schedule 1 is similar to that under the Matrimonial Causes Act 1973, in that the court considers all the circumstances, giving first consideration to the welfare of any child of the family under 18.
The Court has the power to vary a school fees order; the applicant must show a material change of circumstances. The recent decision of A v H (Variation of School Fees Order) [2024] EWFC 254 (B) illustrates the principle of a variation of school fees, albeit this decision predates the VAT change.
The Court is likely to consider the following three issues when deciding these applications –
Affordability, evidenced. Figures showing what the increase does to income and outgoings, not a submission that fees have risen. GW v GH [2023] EWFC 298 (B) shows that even where children have been ordered to attend a named fee-paying school, a judge may still find the fees unaffordable.
Welfare and disruption. A child in the final year of A levels is in a different position from one entering year 7.
Proportionality. A contested application over one term’s fees can cost more than the sum in dispute. On stepped orders referable to fees ceasing, see Aburn v Aburn [2016] EWCA Civ 72.
In general, if the school fees are affordable and the parents are in agreement as to their children being privately educated, the Court is likely to make the order for the payment of the fees.
If there is an issue of principle as to whether the children are to attend a fee-paying school, rather than state education, this is an issue which would need to be considered within the context of s8 of the Children Act 1989 and, likely, an application for a specific issue order.
It is crucial that the party seeking to argue the unaffordability of the fees clearly evidences the cashflow difficulties that they will face if the order is not varied. The judges at district judge level do not have sufficient time during their busy lists to undertake this analysis. The party making the application should provide, as clearly as possible, their concerns as to affordability. This will also assist the responding party to consider the overall merits of the variation application.
Flexibility or Finality? What Tracey v Tracey Decided
The Court of Appeal addressed the choice between a variable order and a capitalised one in Tracey v Tracey [2006] EWCA Civ 734, in which I appeared as junior counsel for the respondent mother. It has been twenty years since the Court heard this appeal and there has been very limited authority on school fees since that time, and very little, if any, further guidance on the capitalisation of school fees.
The circumstances in Tracey were fairly unique. A 2001 consent order placed the school fees obligation on the father, a trader. A 2002 order secured the fees, but the security ran for only 12 months. His trading then deteriorated, and he gave notice that he could no longer afford private education for his two sons. He applied to vary; the mother cross-applied for a lump sum of £272,771 to commute the fees to the end of secondary education, which Bennett J granted.
The Court of Appeal allowed the appeal in part, on an accounting error and on fresh medical evidence bearing on the father’s earning capacity. Exercising the discretion afresh, Thorpe LJ held there had to be security for the boys’ education, and framed the choice as between a secured periodical payments order and a lump sum. Secured payments offer flexibility; the lump sum, he held, carries the great attraction of finality, eliminating the risk of future litigation. He favoured finality, but expressly a finality that does not reach beyond the reasonably predictable, and deleted the part covering fees at a school the younger boy would not join for three years.
The sharpest point is a drafting one. Thorpe LJ observed that had the security been of indefinite duration rather than 12 months, the litigation would not have been necessary at all. A time-limited security clause is a future application waiting to happen.
When the Labour government included the VAT provision in their manifesto, many private schools sought to plan ahead for the increase and invited parents to pre-pay the school fees. Subsequently, the government tightened up the provisions to close this loophole.
In my experience, the majority of cases that come before the Court on the issue of school fees relate to the annual payment of those fees, not for capitalisation for the remainder of the term (save in circumstances where, for example, a child is undertaking their A level studies for a defined period of time). The issue for parents with capitalisation of fees at present is that this does not necessarily safeguard them against any future increases in fees.
How Should Provision Be Structured?
Four structures are commonly used: periodical payments from income, flexible but variable; secured provision, which reduces default risk for as long as the security runs; a ring-fenced fund; and capitalisation by lump sum.
There is also a VAT trap. Pre-payments made on or after 29 July 2024 relating to terms from 1 January 2025 carry VAT under anti-forestalling. Earlier payments are only effective if they fixed a genuine tax point on defined supplies. The normal VAT assessment window is four years, although longer limits may apply in some circumstances. HMRC assesses the school, but school terms generally recover the VAT from the fee-payer. Who bears it as between separated parents is untested, so any order capitalising fees should allocate responsibility for a later assessment expressly.
Six Drafting Points for Orders Being Made Now
- State whether the obligation is inclusive of VAT, and what happens if the rate changes.
- Where fees are capitalised, build in an assumed rate of future increase, and say what happens if it is exceeded.
- Allocate responsibility for any later VAT assessment on fees already paid or pre-paid.
- Define “school fees” by reference to the invoice, and list what is in and out.
- If provision is secured, make the security run for the duration of the obligation. This is the Tracey point.
- Record that the school contract sits separately, and say who is liable to the school if payment fails.
What If the Other Parent Stops Paying?
In circumstances where one parent stops paying, the other parent should make contact with the school as soon as possible to ensure that the child’s school place is not at risk. The parent should notify the bursar of the situation. The school may have a payment plan or bursary provision which could assist the family. Both parents should be mindful of the school’s notice period and establish what the school’s expectations are about the notice period before deciding anything about moving the child.
Is Arbitration Better Than Court?
It can be. A school fees dispute is a narrow issue with a defined value, which suits family arbitration under the IFLA Financial Scheme. A determination can potentially be produced in weeks rather than months. The parties agree to be bound by the award, although the court retains a supervisory and review role when asked to embody it in an order: see S v S (Financial Remedies: Arbitral Award) [2014] EWHC 7 (Fam), which endorsed the scheme, and Haley v Haley [2020] EWCA Civ 1369.
Arbitration cannot be started unilaterally. The scheme requires an agreement signed by both parties or their representatives, so it is an option to propose rather than to impose. Since 29 April 2024, the court can, however, adjourn for non-court dispute resolution without the parties’ agreement under Part 3 of the Family Procedure Rules, and reflect an unreasonable refusal in costs under FPR 28. 3.
Arbitration is an ideal solution for a school fees dispute. On the basis that the evidence has been exchanged and the Form ARB1FS has been signed, the arbitration can be listed at the parties’ (and arbitrator’s) convenience. The parties have the benefit of selecting their tribunal and can enquire before engaging the arbitrator how quickly the award is likely to be available.
What to Do Before the Term Settles
- Read the fees clause in the order. Whether VAT sits inside or outside the obligation decides which parent has the problem.
- Read the school contract and establish who signed, what notice is required, and what is payable in lieu.
- If provision is secured, check how long the security runs. If fees were pre-paid, check whether the payment fixed a tax point.
- Then consider the route. Where affordability has genuinely changed, take advice promptly on a variation application, or propose arbitration to the other parent. Waiting for December will not remove the tax.
The Harcourt Finance Group acts across the full range of financial remedy and Schedule 1 work, and several members, including Suzanne Syme, sit as family finance arbitrators.
Instruct Suzanne Syme
To discuss a school fees variation, the structuring of provision, or a single-issue arbitral reference, contact the clerks at Harcourt Chambers.
Contact: 020 7353 6961 │ clerks@harcourtchambers.co.uk
Frequently Asked Questions
My ex will not pay the school fees. What are my options?
Notify the bursar first, because the school has its own remedies. Then consider enforcing the order, or varying it if circumstances have changed. Where both parents are parties to the enrolment contract, the school may pursue either of you for the whole sum.
Can I claim school fees as part of child maintenance?
Private-school tuition is not included in the standard Child Maintenance Service calculation, which runs on gross income up to £156,000 a year. Fees are dealt with separately, on divorce or under Schedule 1 to the Children Act 1989.
If I pre-paid fees before the VAT came in, am I safe?
Not necessarily. Pre-payments from 29 July 2024 relating to terms from 1 January 2025 carry VAT. Earlier payments are only effective if they fixed a genuine tax point on defined supplies. The normal assessment window is four years, although longer limits may apply. School terms generally pass an assessment back to the fee-payer.
Does provision continue into university?
It can. Section 29(3) of the Matrimonial Causes Act 1973 and paragraph 3(2) of Schedule 1 to the Children Act 1989 both allow orders to continue beyond 18 where the child is in education or training. How far depends on the order and the resources available.
This article is for general information only and does not constitute legal advice. The law is correct as at the date of publication. Specific advice should always be taken to account for individual circumstances. This article includes general information about the VAT rules but does not constitute tax advice. Advice from a suitably qualified tax adviser should be obtained where pre-payments or historic assessments are involved.
Sources
- Finance Act 2025, sections 47 to 49
- GOV.UK, “Applying VAT to private school fees”
- Matrimonial Causes Act 1973, sections 23, 29, 31 and 32
- Children Act 1989, section 8 and Schedule 1
- Human Rights Act 1998, section 4
- Child Support Maintenance Calculation Regulations 2012, regulations 46 and 66
- Family Procedure Rules, Parts 3 and 33 and rule 28.3
- Tracey v Tracey [2006] EWCA Civ 734
- R (ALR and others) v Chancellor of the Exchequer [2025] EWHC 1467 (Admin)
- R (BYL) v Chancellor of the Exchequer [2026] EWCA Civ 170
- James v Seymour [2023] EWHC 844 (Fam); A v H [2024] EWFC 254 (B); GW v GH [2023] EWFC 298 (B)
- Aburn v Aburn [2016] EWCA Civ 72; BR v SN [2024] EWHC 1512 (Fam)
- S v S (Financial Remedies: Arbitral Award) [2014] EWHC 7 (Fam); Haley v Haley [2020] EWCA Civ 1369
- Institute of Family Law Arbitrators, Financial Scheme Rules